Operations Stories
Meliá Just Walked Away From 15 Cuban Hotels. The Dominos Aren't Done Falling.

Meliá Just Walked Away From 15 Cuban Hotels. The Dominos Aren't Done Falling.

Meliá's pullback from nearly half its Cuban portfolio isn't really about Cuba. It's about what happens when geopolitics, energy collapse, and sanctions converge on properties where occupancy already cratered to 34%... and what that playbook looks like when it shows up closer to home.

Available Analysis

I've been in rooms where the decision to exit a market gets made. It's never one thing. It's never the headline reason. It's the accumulation... the slow bleed that everybody watches and nobody wants to name until somebody finally says it out loud. Meliá just said it out loud about Cuba, pulling management, branding, and commercial services from 15 of their 34 hotels on the island. Effective immediately. And if you read between the lines of their corporate language about "responsible business conduct" and "orderly operational frameworks," what you're really hearing is a company that did the math and realized the math stopped working a long time ago.

Here's what that math looks like. First quarter 2026, Meliá's Cuban properties ran 34% occupancy. Down 6.5 points from the year before, which was already terrible. Historical average for these properties was around 60%. The island pulled in 328,000 international tourists between January and April... less than half of the prior year. Airlines are canceling routes. Visa and MasterCard just suspended operations on the island. The energy grid is so unreliable that Meliá themselves acknowledged most of the 15 properties they're exiting were already non-operational. They weren't running hotels. They were maintaining the fiction of running hotels while the lights flickered on and off and the guests stopped coming. That's an important distinction. When a management company tells you "the financial impact is limited because most of these were already non-operational," what they're really telling you is they've been carrying dead weight on the books and they finally cut the rope.

The trigger here was the U.S. sanctions deadline... June 5, companies had to sever ties with GAESA, the Cuban military-linked conglomerate that controls much of the island's tourism infrastructure through its subsidiary Gaviota. Meliá routed operations through a Portuguese subsidiary, but the writing was on the wall. Iberostar pulled back. Blue Diamond pulled back. Airlines pulled routes. When your distribution channels, your payment processors, and your airlift all disappear in the same quarter, you don't have a hotel operation anymore. You have a building with beds in it. I watched something similar happen once at a resort property caught between a government dispute and a brand that kept hoping the situation would resolve itself. It didn't resolve itself. It never does. The operators on the ground knew it was over months before anyone at headquarters would admit it. The people who work in those buildings always know first.

What makes this worth paying attention to... even if you're running a 180-key Hilton Garden Inn in Omaha and Cuba feels like another planet... is the pattern. Geopolitical risk isn't theoretical anymore. Sanctions regimes are expanding. Energy reliability is a variable in markets that never used to worry about it. Airlift decisions are being made on political grounds as much as commercial ones. And management companies are demonstrating, very publicly, that when the operating environment deteriorates past a certain point, they will protect their brand and their balance sheet before they protect the property or the people in it. That's not a criticism. That's the business model working exactly as designed. The management company's risk is reputational and contractual. The owner's risk is the building, the debt, and the employees. Those are very different exposures, and Cuba just showed you what the gap looks like when it cracks open. Thousands of Cuban hospitality workers are about to find out what "orderly transition" means for them. I've seen orderly transitions. They're orderly for headquarters. They're chaos at property level.

The question nobody at the conferences wants to ask is whether this pattern stays contained. Right now it's Cuba. But the underlying mechanics... sanctions pressure, energy instability, currency risk, collapsing demand, airlines pulling capacity... those aren't uniquely Cuban problems. They're stress-test scenarios that asset managers run on paper and hope never materialize. Meliá just lived through the materialization. If you're an operator or an owner with international exposure, or even domestic exposure in markets where one or two of these variables could shift, this isn't a story about the Caribbean. This is a preview.

Operator's Take

This one's for anyone managing or owning properties with international brand affiliations, or properties in markets dependent on specific airlift, a single demand generator, or government-adjacent economics. Pull out your management agreement this week and find the force majeure and termination clauses. Know exactly what triggers an exit for your management company and what your exposure looks like if they exercise it. This is what I call the Shockwave Response... you need to know your floor and your breakeven before the shock hits, not after. If you're in a market where energy reliability, political risk, or airlift concentration is even a moderate concern, stress-test your P&L against a 30% demand drop with simultaneous cost inflation. Don't wait for your version of Cuba to show up in your inbox. The operators who survive external shocks are the ones who already ran the scenario and had a plan in the drawer. Be that operator.
Read full analysis → ← Show less
Source: Google News: Hotel Industry
Airbnb Just Told Hotels Exactly What Guests Want This Summer. Most Hotels Aren't Listening.

Airbnb Just Told Hotels Exactly What Guests Want This Summer. Most Hotels Aren't Listening.

Airbnb's summer travel data shows one-third of travelers choosing rural, activity-driven trips over traditional destinations. If you're a hotel operator wondering why your summer leisure pace is soft, the answer might be that your property is selling a bed when the guest is buying an experience.

Available Analysis

So Airbnb dropped their 2026 summer travel trends report, and buried inside the marketing language about "playcations" is something hotel operators should actually pay attention to. One-third of summer travelers are staying closer to home, booking rural properties near golf courses, surf breaks, and lakeside recreation areas. Searches for activity-driven listings more than doubled. That's not a trend piece for a lifestyle magazine. That's demand data telling you where the leisure dollar is going... and it's not going to your lobby.

Look, I get it. "Playcations" sounds like something a PR team invented during a brainstorm with too many kombucha seltzers. But strip away the branding and what Airbnb is actually reporting is a fundamental shift in how leisure travelers define value. They're not searching for "hotel near downtown." They're searching for "place near the thing I want to do." The accommodation is secondary to the activity. And here's what that means for hotels: if your property's value proposition starts and ends with "clean room, good location, free breakfast," you're competing on a dimension the guest has stopped prioritizing. You're selling inputs. They're buying outcomes.

I talked to an independent operator last month who runs a 140-key property about 20 minutes from a popular lake recreation area. She told me she started listing kayak and paddleboard rentals on her website... not as a separate booking, just information about where to get them nearby, with driving directions and a suggested itinerary. No technology investment. No app. Just a page on her existing site. Her direct bookings from organic search jumped 18% in the first quarter she did it. Why? Because Google started surfacing her property for activity-related searches instead of just "[city name] hotel." She didn't build a platform. She just answered the question the guest was actually asking.

Here's what bugs me about the hotel industry's response to this kind of data. When Airbnb publishes that activity-driven travel is surging, the brand response is usually some version of "we're launching an experience-curated partnership ecosystem" (I think I just threw up in my mouth a little). The technology response is "here's an AI-powered concierge chatbot." Neither of those actually solves the problem. The problem is discoverability. Guests searching for "best places to surf near [destination]" are finding Airbnb listings because those listings describe the activity, not the property. Most hotel websites describe the property. The amenities. The room types. The brand loyalty points. All stuff the guest already assumes exists. Nobody's searching for "hotel with a fitness center." They're searching for "weekend golf trip under $200 a night." The technology gap here isn't AI or chatbots... it's basic content strategy and SEO that most hotel websites haven't updated since 2019.

The deeper structural issue is that Airbnb's 17% active listing growth means supply keeps expanding in exactly the markets where this demand is heading... rural, recreation-adjacent, experience-driven. Hotels in secondary and tertiary markets near outdoor recreation are going to feel this compression first. Your comp set isn't just the Hampton Inn down the road anymore. It's the three-bedroom cabin on the lake that sleeps eight, has a full kitchen, and costs $175 a night. That's a per-person value proposition most select-service hotels can't touch on paper. What you CAN compete on is reliability, consistency, service, and the fact that nobody has ever shown up at a hotel and found the "amenities" were a broken hot tub and a host who doesn't respond to texts. But you have to actually articulate that value in the language the guest is using to search. And right now, most hotels aren't even in the conversation.

Operator's Take

If you're running a property anywhere near outdoor recreation... lake, coast, trails, golf... pull up your website right now and ask yourself: does this site answer the question "what can I DO here?" or just "what does the room look like?" If it's the second one, you're invisible to the fastest-growing leisure segment this summer. This week, build a simple "things to do" page with specific activities, distances, and local recommendations. Cost you nothing. Takes a couple hours. Then check your Google Search Console in 60 days and tell me your organic traffic didn't move. For branded properties, talk to your DOS about updating your OTA listing descriptions to include activity-specific keywords... "near [lake/trail/course name]" isn't brand dilution, it's revenue capture. The guests Airbnb is winning right now aren't lost to you. They just can't find you because you're not speaking their language.

— Mike Storm, Founder & Editor
Read full analysis → ← Show less
Source: Google News: Airbnb
Philly Killed the Hotel Tax Hike. Here's Why That Almost Didn't Happen.

Philly Killed the Hotel Tax Hike. Here's Why That Almost Didn't Happen.

Philadelphia's City Council just rejected a proposed hotel tax increase that would have pushed the city's total hospitality tax burden to 17.5%, the highest on the East Coast. The fact that it got as far as it did should worry every operator in a major metro.

Available Analysis

So let me walk you through what almost happened in Philadelphia. The mayor proposed bumping the hotel tax by 2 full percentage points... from 15.5% to 17.5%... to fund homelessness services and school district gaps. When the industry pushed back (hard), the number got revised down to a 0.6% increase. And then City Council killed even that.

Good news, right? Sure. For now.

But here's what actually matters about this story. The School District of Philadelphia has a $300 million structural deficit. The federal COVID relief money is gone. The city needs $48 million a year just to keep school-based positions from getting cut. And the mayor's instinct... her first instinct... was to look at hotels, rideshare, and short-term rentals as the ATM. A $1-per-ride tax on Uber and Lyft. A 6% bump on Airbnb-style rentals. And the hotel tax hike. The combined short-term rental and hotel increases were supposed to generate $75 million over five years. That's not a one-time ask. That's a revenue structure designed to be permanent.

Look, I get why City Council rejected it. They cited cost of living concerns, the impact on businesses, and the fact that the hotel tax change would have needed state enabling legislation that wasn't going to happen in Harrisburg anyway. But the political instinct is the thing I'm watching. When a city has a budget hole, hospitality is always the first pocket they reach into because tourists don't vote. The industry groups... the hotel association, the convention bureau, the restaurant and lodging association... had to mobilize hard to stop this. Uber said over 90,000 letters were submitted opposing the rideshare tax alone. That's a massive defensive effort just to maintain the status quo.

And here's the part that should keep you up at night if you operate in any major city. Council approved a one-time $48 million allocation from existing funds for the school district. One-time. The deficit is structural. Which means next budget cycle, or the one after that, someone's going to propose this again. Maybe not in Philly. Maybe in your city. The playbook is identical everywhere... municipality has a funding gap, hotels and short-term rentals are "luxury" services that can absorb a tax increase, and the political cost of taxing visitors is zero compared to taxing residents. I talked to an owner last year who operates in three different metros and told me he now budgets a line item for "tax defense"... not the taxes themselves, but the lobbying cost to prevent new ones from passing. That's where we are.

The FIFA World Cup and MLB All-Star Game are coming to Philly. At 17.5%, the city would have been pricing itself above New York, Boston, DC, Baltimore, and Atlanta on total hotel tax burden. Council understood that. But the pressure to find revenue somewhere isn't going away just because they said no this time. If you're running hotels in any top-25 metro, the question isn't whether your city will try this. It's when.

Operator's Take

Here's what I'd be doing right now if I operated in any major metro market. First... know your total tax burden as a percentage of room revenue, not just the rate. Your guests don't see "city tax" and "state tax" and "tourism assessment" separately. They see the total on the folio. If you're already north of 15%, you're in the zone where every additional point starts showing up in booking hesitation and OTA comparison shopping. Second... get involved with your local hotel association's government affairs committee before the next budget cycle, not during it. The Philadelphia industry won because they were organized. Not every market has that infrastructure. If yours doesn't, build it now. And third... watch what happens with that $300 million school deficit. One-time money doesn't fix structural problems. This fight is coming back, in Philly and in a city near you. The operators who see it coming are the ones who won't be scrambling when the next proposal drops.

— Mike Storm, Founder & Editor
Read full analysis → ← Show less
Source: Google News: Airbnb
75 Million Summer Passengers. But Your Nonstop From Dallas Just Disappeared.

75 Million Summer Passengers. But Your Nonstop From Dallas Just Disappeared.

Airlines are projecting record-breaking summer travel while simultaneously cutting routes because jet fuel hit $15 a gallon at LAX. If your hotel's feeder market depends on a route that just got suspended, the macro headline is worse than useless... it's a distraction.

Available Analysis

I worked with a revenue manager once who had the best wall in any hotel I've ever seen. Not awards. Not thank-you letters. A map. Pushpins for every city that fed her property more than 50 room nights a year, with colored string connecting them to the airlines that served those routes. When I asked her why she didn't just use the data in the RMS, she said something I've never forgotten: "The system tells me where guests came from. The map tells me how they got here. When the how changes, the where follows about 90 days later."

That map is what every revenue manager at an airport-adjacent or air-travel-dependent hotel needs to be building right now... metaphorically or literally. American Airlines is projecting 75 million passengers this summer across 750,000 flights. That's a record. That's genuinely strong demand. And it is also almost completely irrelevant to you if your property depends on a route that just got axed. American suspended six domestic routes effective August 5 through October 5. Four of them out of LAX... to Cleveland, Columbus, Pittsburgh, and Washington Dulles. Two from Charlotte to Ontario and Sacramento. The reason is $15-a-gallon jet fuel at LAX (up 50% since the Iran situation escalated in March) and a system-wide fuel bill that's climbing by over $4 billion this year. They're not the only ones. Norse Atlantic killed all LAX-to-Europe summer service back in April. Allegiant rerouted LAX operations to Burbank in January. Spirit is gone entirely. JetBlue just raised its Q2 fuel cost guidance to over $4.30 a gallon. United's CEO is projecting 15-20% ticket price increases. This is not one airline having a bad quarter. This is a structural reshuffling of where passengers fly, how much they pay, and which markets win or lose seats.

Here's what this means at property level, and it's different depending on where you sit. If you're running a hotel near LAX, you're about to see a net reduction in connecting passengers and potentially in overnight stays. Four fewer American routes means fewer passengers with layovers, fewer missed connections, fewer "I'll just grab a hotel tonight and fly out in the morning" bookings. If you're in Cleveland, Columbus, Pittsburgh, or Dulles and your transient mix includes guests who flew nonstop from LA... that's gone until at least October. United still operates on all four of those routes, so the demand doesn't vanish entirely, but it concentrates onto fewer flights with higher fares. Higher fares mean fewer leisure travelers. Fewer leisure travelers mean your weekend pace is about to soften. If you're in a secondary leisure market that depended on one or two carriers for nonstop service from a major hub... you already know this feeling, because we lived through it during COVID recovery when routes came back unevenly. Some markets got their airlift back in months. Some waited years. Some are still waiting.

What bothers me about the 75 million number is how easy it is to hide behind. It's this massive, reassuring headline that makes everyone feel good about summer. And system-wide, demand IS strong. But system-wide demand is a national weather report. You don't staff your pool deck based on the national forecast. You look out your window. This is what I call the National Number Trap... the macro data tells a story that's true at 30,000 feet and potentially dead wrong at your property. Your revenue management decisions need to be made at the route level right now, not the system level. Pull your forward booking pace by feeder market. Cross-reference it against every published route suspension you can find (not just American... check JetBlue, check Spirit's old routes that nobody backfilled, check whether your regional carrier has quietly reduced frequency). The information is out there. The airlines publish schedule changes. Your GDS data shows booking pace by origin. If you're not connecting those two data sets right now, you're flying blind. Pun intended.

One more thing worth watching. The FAA has capped operations at O'Hare at 2,708 daily through October and extended caps at Newark through the same period. Construction, gate constraints, controller staffing... the usual alphabet soup of reasons. But the effect is real. Fewer operations means more delays, more misconnects, more passengers who end up needing a room they didn't plan on. If you're an airport hotel near a capped hub, that's actually a demand driver... but only if you're positioned to capture it. Walk-in rates. Mobile booking. Making sure your front desk knows to quote the rack rate with a smile when a tired passenger walks in at 10 PM because their connection evaporated. That revenue opportunity exists. But it's a Tuesday-at-10-PM opportunity, not a strategy-deck opportunity. It happens at the desk or it doesn't happen at all.

Operator's Take

If you're running a hotel that depends on air travel for more than 30% of your transient mix, stop what you're doing this week and pull your forward booking data by origin city. Match it against current airline schedules for August through October. If you see a route that's been suspended or reduced in frequency, adjust your forecast now... not in three weeks when the pace report confirms what you already could have known. For airport-adjacent properties near capped hubs like O'Hare and Newark, train your front desk team on walk-in conversion. Misconnects and delays are going to spike this summer, and every one of those stranded passengers is a potential $189 room night if your team handles it right. For properties in secondary markets that just lost nonstop service, start building your drive-to marketing now. The guest who used to fly nonstop from LAX to your market didn't stop wanting to visit. They just need a different reason to make a four-hour drive instead.

Read full analysis → ← Show less
Source: News
Chesky Just Sold $128M in Airbnb Stock. His Remaining Stake Still Controls the Board.

Chesky Just Sold $128M in Airbnb Stock. His Remaining Stake Still Controls the Board.

Airbnb's CEO dumped nearly a million shares over nine days while simultaneously announcing an AI lab and new service verticals. The sale is pre-planned and legal, but the number underneath it tells you exactly how the company's leadership is pricing its own growth story.

$128.5 million in Class A share dispositions across nine trading days, May 27 through June 4. Approximately 961,510 shares at a weighted-average price between $132 and $138. Chesky still holds north of 10.85 million shares directly, plus indirect stakes through trusts. The filing says Rule 10b5-1 plan, adopted February 26, 2026. Pre-arranged. Automatic. Nothing to see here.

Let's decompose this. Chesky sold roughly 8.9% of his direct holdings in a single week. The 10b5-1 plan was adopted three months before these sales executed, which means in late February, someone (or someone's wealth advisor) looked at Airbnb's trajectory and decided that $132-$138 per share was an acceptable exit price for nearly a billion-dollar chunk of personal net worth. That's not a panic sale. It's a price target. And it was set while the stock was trading within 10% of its 52-week high of $147.25. The CFO sold the same week... 7,433 shares under her own 10b5-1 plan adopted a full year earlier. Two C-suite insiders, two separate plans, same execution window.

The timing is worth noting not because of the plan (plans are plans), but because of what Airbnb announced around the same dates. Q1 revenue came in at $2.68 billion, beating consensus by $60 million. EPS missed at $0.26 versus $0.31 expected. Then came the Summer Release on May 20... car rentals, grocery delivery, boutique hotels, the full platform expansion playbook. Then the AI lab announcement on June 4. Revenue beat, earnings miss, aggressive diversification, and the CEO is selling. The read isn't complicated: top-line growth is real, bottom-line conversion is getting harder, and the people closest to the numbers are taking chips off the table at current valuations.

For hotel investors and asset managers watching Airbnb's competitive positioning, the product expansion matters more than the stock sale. Boutique hotels on the Airbnb platform is a direct channel play against independent properties that currently rely on OTA distribution. Car rentals and grocery delivery are stickiness features... they keep the traveler inside the Airbnb ecosystem for the full trip, not just the accommodation. Every dollar Airbnb captures in adjacent services is a dollar that doesn't flow through your lobby, your F&B outlet, or your concierge recommendations. The AI lab is the infrastructure bet underneath all of it... better matching, better pricing, better host tools, all of which compress the quality gap between a well-run Airbnb and a mediocre hotel.

ABNB dropped 2.6% to $134.26 after the filings hit. Analyst consensus remains "Moderate Buy" with price targets from $162 to $168. That's a 20-25% implied upside from current levels, which means Wall Street is pricing in the platform expansion thesis even while insiders are selling at today's price. One of those positions will be wrong. If you own or operate hotels competing against Airbnb supply in leisure markets, the safer assumption is that the analysts are right and the platform gets stronger... because the downside of being wrong about that assumption is a lot more expensive than the upside.

Operator's Take

Here's what this actually means if you're running an independent or soft-branded property in a leisure market. Airbnb isn't just your competitor for the overnight stay anymore... they're building a full-trip platform. Car rentals, groceries, experiences, all inside one app. Every service they add is one more reason a guest books there instead of with you. If your direct booking strategy still starts and ends with a "Book Direct" button on your website, you're losing ground. Call your revenue manager this week and audit what percentage of your comp set's demand is going to short-term rental platforms. Then look at your ancillary revenue per guest... F&B, parking, experiences... and ask whether you're capturing enough wallet share to justify your rate premium over an Airbnb down the street. That's where the real fight is now. Not room night versus room night. Dollar versus dollar across the full trip.

— Mike Storm, Founder & Editor
Read full analysis → ← Show less
Source: Google News: Airbnb
Airbnb Lost 83% of Its NYC Listings. Now It Wants Them Back Before the World Cup.

Airbnb Lost 83% of Its NYC Listings. Now It Wants Them Back Before the World Cup.

CICC just slapped an Outperform rating on Airbnb with a $165 target, and Airbnb is pushing hard to loosen New York City's short-term rental crackdown before the 2026 World Cup floods the market with demand. The question for hotel operators isn't whether Airbnb succeeds... it's what happens to your rates either way.

Available Analysis

So here's the setup. New York City passed Local Law 18 in 2023, requiring hosts to register, be physically present during stays under 30 days, and cap guests at two per booking. Active short-term Airbnb listings in the city dropped from 21,900 to 3,700 in a single year. That's an 83% decline. Hotels filled the gap. Room rates climbed roughly 6% in 2024. For traditional operators in Manhattan, Brooklyn, and Queens, the regulatory crackdown was the best demand driver nobody had to pay for.

Now Airbnb wants that supply back. And the timing isn't accidental... the 2026 FIFA World Cup hits the US this summer, and Airbnb's argument basically writes itself: "You're going to need every bed in the five boroughs, and we can deliver 20,000 of them if you let us." Two bills are sitting in the NYC Council right now that would loosen restrictions for one- and two-family homes, potentially allowing host-absent rentals and more guests. Meanwhile, incoming Mayor Zohran Mamdani has publicly opposed easing the rules. So we've got a regulatory tug-of-war playing out against a hard deadline of a global sporting event. That's the tension.

Look, I've watched this exact pattern before in markets where STR regulation gets loosened after a crackdown. What actually happens is messy. Supply doesn't come back gradually... it floods. Hosts who converted to 30-plus-day rentals switch back overnight. New hosts enter because the friction is lower. And the rate premium hotels enjoyed during the restricted period? It compresses. Fast. Not because hotels did anything wrong, but because the supply dynamics that were propping up ADR just... shifted underneath them. If you're an operator in New York running pro formas based on 2024-2025 rate levels, you need to stress-test against a scenario where 10,000 to 15,000 Airbnb listings reappear within six months of any regulatory change.

The CICC initiation is interesting context here. A $165 price target on Airbnb (roughly 20% upside from recent trading) with an Outperform rating tells you what the investment community is pricing in: they believe Airbnb's regulatory headwinds are temporary. The average analyst target sits around $161. That's a lot of smart money betting that cities like New York will eventually bend. Whether that's right or not, the signal matters for hotel operators because it means Airbnb has the capital, the investor backing, and the strategic incentive to keep pushing. This isn't a company that's going to quietly accept an 83% reduction in one of its most valuable markets.

Here's what actually matters for operators outside New York, though. Every city watching this fight is taking notes. The NYC playbook... registration requirements, host-present mandates, guest caps... has become the template for STR regulation everywhere. If Airbnb gets concessions in New York, even partial ones, it becomes the precedent that every other city council considers. And if Airbnb loses, the template hardens. Either way, the outcome in New York is going to ripple through every market where hotels and STRs compete for the same guest. I talked to an independent operator in a major East Coast city last month who told me he'd built his entire renovation ROI model on the assumption that local STR restrictions would hold. "If they loosen up," he said, "my payback period goes from seven years to never." That's not hyperbole. That's the math when your rate premium depends on a regulatory moat you don't control.

Operator's Take

If you're running a hotel in New York or any market with active STR restrictions, this is your wake-up call to stop treating regulation as a permanent competitive advantage. It's not. It's a window. Run your current ADR against a scenario where short-term rental supply in your comp set increases 30-50% within a year. If your margins only work at today's restricted-supply rates, you've got a structural problem, not a strategy. For GMs in World Cup host cities specifically... start having the rate integrity conversation with your revenue team now, before the event demand masks the supply shift happening underneath it. And bring this to your ownership group before they read about Airbnb's lobbying push in the Wall Street Journal and start asking questions you haven't thought through yet. The operators who built loyalty, direct booking channels, and genuine service differentiation during the STR crackdown will keep their guests. The ones who just rode the rate wave are about to find out what their hotel is actually worth to the market.

— Mike Storm, Founder & Editor
Read full analysis → ← Show less
Source: Google News: Airbnb
Your Pool Is Empty Six Hours a Day. Someone Else Will Sell Tickets to It.

Your Pool Is Empty Six Hours a Day. Someone Else Will Sell Tickets to It.

Long Island hotels are charging $50 to $500 for day passes to pools and spas that sit half-empty most of the week. The real question isn't whether this works... it's what happens to your overnight guest experience when the pool deck belongs to someone who didn't check in.

Available Analysis

I watched a GM lose his mind over a pool towel inventory about fifteen years ago. Not the cost of the towels (though that was part of it). The issue was that his pool was packed on a Saturday afternoon, his housekeeping team was running towels back and forth like a bucket brigade, and half the people out there weren't even guests. They were locals who'd wandered in through a side gate. He had all the demand in the world and zero way to monetize it. He was giving away capacity for free and paying the labor cost to service it.

That memory is why this Long Island day pass story hit me differently than it'll hit most people. Newsday just profiled a handful of properties out there... Gurney's charging $150-$160 for spa day access, Hotel Indigo East End starting at $50 for pool time, Canoe Place selling daybeds at $500 with a $150 F&B minimum. Those numbers are real. And the platform driving most of this, ResortPass, now has over 2,000 hotel partners and just inked a multiyear deal with Marriott. This isn't a novelty. This is a revenue line that didn't exist five years ago for most properties, and it's growing fast enough that the big brands are building infrastructure around it.

Here's what I think people are missing, though. The upside is obvious... you're selling access to amenities during hours when they'd otherwise sit idle. The industry stat floating around is that day pass users spend two to three times more on property than overnighters. Think about that. Your pool bar, your spa retail, your restaurant covers... all incremental. A well-run day pass program at a resort-style property can generate north of $2M annually in ancillary revenue. That's real money. That changes your P&L. But the downside is the thing nobody wants to talk about in the press release. You are fundamentally changing who is on your property, when, and why. Your overnight guest paying $400 a night expects a certain experience at the pool. When that pool is now shared with 30 day pass holders who paid $50 each, you've got a math problem and a service problem happening simultaneously. The math works beautifully on a Tuesday in May. It gets dicey on a Saturday in July when your paying guests can't find a lounge chair.

The operational complexity here is where most properties stumble. Your PMS wasn't built to manage day guests. Your front desk team is checking in overnighters. Who handles the day pass arrival... the pool attendant you don't have? The hostess who's also running the restaurant? Towel distribution, F&B ordering, incident management, parking... every one of these is a workflow that needs to be designed, staffed, and managed. I've seen hotels try to bolt this onto existing operations without adding a single labor hour and wonder why their TripAdvisor scores dropped in the same quarter their ancillary revenue went up. You traded one problem for another. That's not strategy. That's whack-a-mole. The hotels doing this well... and some are doing it very well... treat day pass operations as a separate business unit with its own staffing model, its own P&L tracking, and clear physical boundaries between day guest spaces and overnight guest spaces. The ones doing it poorly are just selling pool access on an app and hoping it works out.

One more thing. The Marriott-ResortPass deal tells you where this is headed. The brands are going to start expecting this revenue line. If you're a franchisee at a full-service or resort property with pool and spa amenities, don't be surprised when day pass revenue shows up as a "recommended program" in your next brand review. And recommended today has a way of becoming required next year. If you're going to do this (and for many properties, you should), get ahead of it. Design it yourself. Control the guest experience on both sides of the equation. Because if you wait for the brand to hand you a turnkey program with a platform fee attached, you'll be paying someone else to sell access to your own pool.

Operator's Take

If you've got a pool, a spa, or any amenity that sits underutilized more than four hours a day, run the numbers this week. Not on the revenue (that part's easy and exciting). Run the numbers on the labor. How many additional staff hours do you need to service day guests without degrading the overnight experience? What's your towel cost increase? What's the incremental F&B labor for that pool bar during extended hours? If the margin still works after you've honestly accounted for those costs, build your own program before your brand builds one for you. Start with weekday-only access. Cap the daily count at 15-20% of your pool capacity. Track overnight guest satisfaction scores weekly from the moment you launch. If satisfaction dips, you've pushed too far. This is what I call the Flow-Through Truth Test... the revenue looks great on the top line, but if it doesn't flow through to GOP after you've staffed it, supplied it, and absorbed the wear on your facilities, you haven't created profit. You've created activity.

Read full analysis → ← Show less
Source: Google News: Resort Hotels
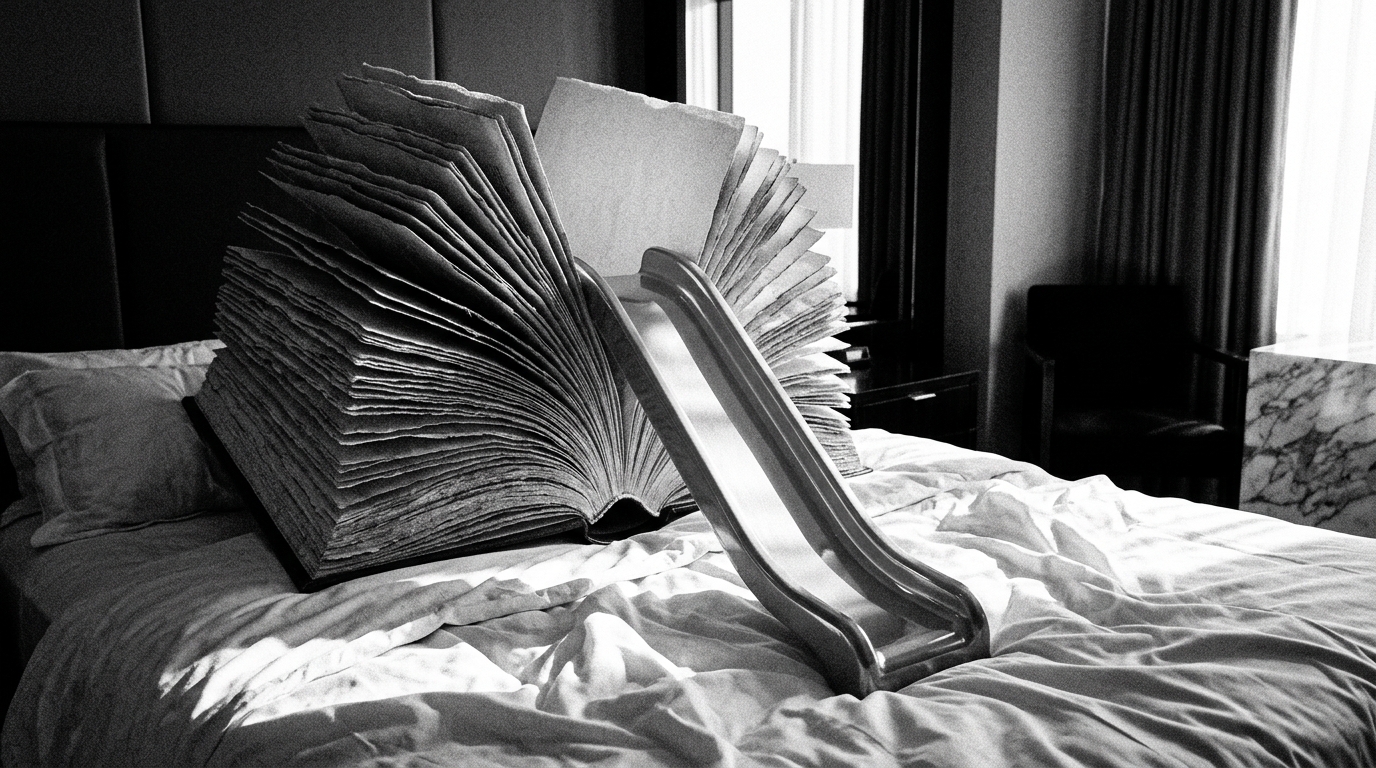
Four Seasons Tianjin Built a Slide Into a Giant Book. Here's Why That's Smarter Than It Looks.

Four Seasons Tianjin Built a Slide Into a Giant Book. Here's Why That's Smarter Than It Looks.

Four Seasons is turning a 437-key luxury hotel in Tianjin into a family destination with themed rooms, curated cultural itineraries, and a summer program designed to fill beds during a season most luxury properties coast through. The play isn't about kids... it's about who's paying for the room.

I worked with a GM years ago who hated the idea of families in his luxury property. Hated it. "We're not a resort," he'd say. "We're a business hotel. Families mess up the lobby vibe." Then his June numbers came in. Then July. Then August. Occupancy cratered while the family-friendly property down the street ran 85%. He called me that fall and said, "So... how do we get kids in here without turning into a Chuck E. Cheese?" That's the question every luxury urban hotel eventually asks.

Four Seasons Tianjin just answered it with a summer program that's more calculated than it appears. They've built themed family rooms with bunk beds shaped like oversized books, slides, interactive game carpets, and craft activities like clay sculpting and kite-making. They've mapped out cultural walking routes to landmarks around the city. And they've wrapped it all in their Executive Lounge package... breakfast, afternoon tea, evening cocktails, the whole progression that keeps a family spending on-property from 6:30 AM to 9:30 PM. That's not a kids' program. That's a revenue architecture disguised as whimsy.

Here's why this matters beyond Tianjin. China's luxury hotel market is growing faster than anywhere else right now, and domestic family travel is the engine. RevPAR across Chinese hotels was projected to climb 7-10% year-over-year this summer, with occupancy peaking around 72-75% in July. Four Seasons isn't chasing that wave accidentally... they're opening properties in Suzhou, Shanghai, Dalian, Hangzhou, Xi'an, and Moganshan over the next few years. This summer program is a pilot for how you position a 437-room urban luxury property as a family destination without diluting the brand. The slide goes in the kids' room, not the lobby. The craft activities happen in a controlled space. The parents get their cocktails at 8 PM. Everyone stays in their lane.

The deeper play is what I'd call a Price-to-Promise Moment, and Four Seasons has always understood this better than most. The moment a family walks into that themed room and their six-year-old sees the slide... that's when the rate justifies itself. Not at check-in. Not when they read the confirmation email. Right there. That moment. And if you're running a luxury property that goes soft in summer because your business travel dries up, that moment is worth engineering. You don't need a book-shaped bunk bed specifically. You need SOMETHING that makes a family feel like this rate, whatever it is, was worth every yuan.

What most operators miss is the economics underneath the experience design. A family booking a themed room with Executive Lounge access at a Five Seasons property in China is spending on a room that would otherwise sit empty or get discounted to a corporate negotiated rate during off-peak. The incremental F&B through the lounge package has dramatically better margins than discounting the room rate to fill it. Four Seasons is essentially converting low-demand nights into premium-rate family experiences. That's not hospitality feel-good... that's revenue management with better set design.

Operator's Take

If you're running a luxury or upper-upscale property that goes soft in summer (or any predictable low-demand period), stop thinking about discounting and start thinking about programming. You don't need Four Seasons' budget. You need one room type, one experience package, and one moment that makes a family say "this was worth it." Go look at your June and July pace right now. Find the nights where you're projecting below 70% occupancy. Those are the nights that need a reason to exist at full rate. A $3,000 investment in a themed family room element pays for itself in two weekends if it lets you hold rate instead of cutting it. Run the numbers on your lounge or F&B package margins against a discounted room-only rate... I promise the package wins. Every time.

Read full analysis → ← Show less
Source: Google News: Four Seasons
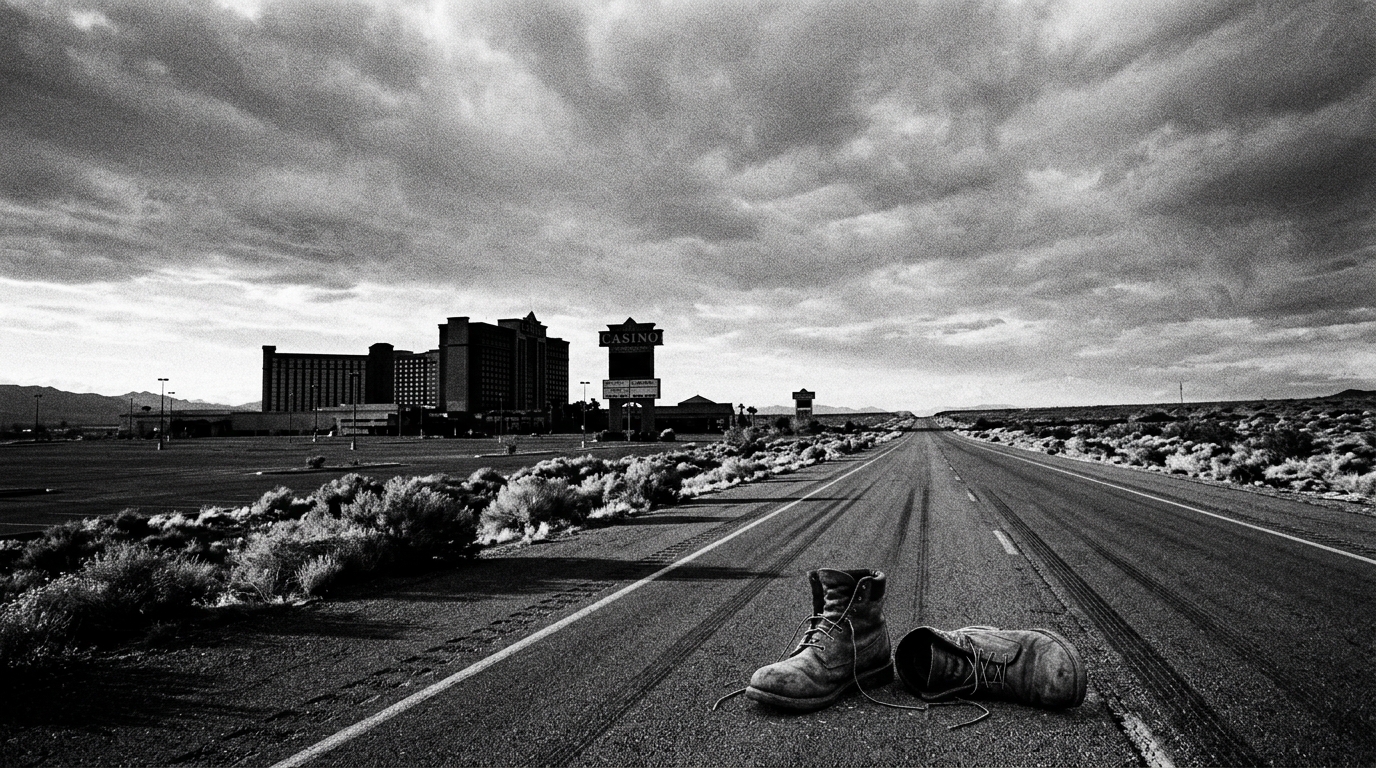
The Primm Family Has Zero Debt and 568 Acres. They Need a Partner by July 4.

The Primm Family Has Zero Debt and 568 Acres. They Need a Partner by July 4.

Affinity Gaming is walking away from Primm, Nevada with $500M in debt and 344 employees about to lose their jobs and their homes. The family that built this town 40 years ago just got the land back for free... and the clock is ticking on whether anyone can keep the lights on.

Available Analysis

I watched a casino town die once. Not Primm... somewhere else, years ago. Different name, same story. The operator couldn't make the math work, the owner held the land, and everybody in between (the dealers, the housekeepers, the bartenders, the maintenance guys who kept 40-year-old HVAC systems breathing) got caught in the middle while the suits figured out who was going to sign the next lease. The town didn't die all at once. It just got quieter. Then the gas station closed. Then the diner. Then it was just a building with a sign that used to mean something.

That's what's staring the Primm family in the face right now, and the timeline is brutal. Affinity Gaming announced May 5 that it's pulling out of everything... Primm Valley Resort, Primm Center, the truck stop, the lotto store. Doors close July 4. That's not a deadline. That's a countdown. Whiskey Pete's already went dark in December 2024. Buffalo Bill's has been running limited operations since last July. Three hundred and forty-four people are about to lose jobs, and here's the part that makes your stomach turn... many of them live in company-owned apartments on the property. They're not just losing paychecks. They're losing their housing.

Now here's where it gets interesting from an ownership perspective. The Primm family still holds 568.5 acres of land. Affinity paid MGM $400 million for the operational rights back in 2007, rode the whole thing into the ground, and now they're walking away carrying (by their own CEO's admission) north of $500 million in total company debt. The Primms? They get their land back with zero debt on the casino operations. That's not a bad hand. In fact, if you're a potential operator or investor, it's a clean slate... no legacy debt, no deferred maintenance obligations from the previous operator's balance sheet, just dirt and buildings at one of the most visible highway intersections between Los Angeles and Las Vegas.

But clean slate and viable operation are two very different things. Affinity's CEO said publicly that Primm is "just not viable as a casino operation." He's not entirely wrong about the headwinds. Southern California tribal casinos have been eating this market alive for years. The drive-through traffic that used to stop in Primm because it was the first legal gambling on the Nevada side now has better options before they ever cross the state line. You can blame COVID's lingering effects, you can blame the competition, but the structural challenge is real... this location needs a reason to stop, not just a reason to pass by. There's talk of a supplemental airport for Southern Nevada projected out to 2037. That's a nice long-term catalyst if you're a land speculator. It's meaningless if you're trying to make payroll next month.

The Primm family's Cory Clemetson says an announcement on a new partner could come within a week. LV Petroleum, a company that runs 84 truck stops nationally, has publicly expressed interest in taking over all operations, including reopening Whiskey Pete's. But Clemetson tamped that down, calling reports of a done deal "overstated and premature" and indicating multiple proposals from "well-established operators" are on the table. Smart move. When you're negotiating from a position of owning the land free and clear, you don't jump at the first offer. You let them compete. But you also don't have the luxury of time when 344 people are watching a July 4 deadline approach and wondering if their town is about to become a ghost story.

Operator's Take

If you've ever operated a property in a market that depends on a single demand generator... a highway exit, a convention center, a military base, a factory... pay attention to this one. The Primm situation is what happens when the demand thesis changes and nobody adjusts the operating model for 15 years. For those of you running properties in secondary or tertiary markets, this is your stress test. Ask yourself: if your primary demand driver disappeared tomorrow, what's your fallback? Not theoretically. Actually. Write it down. And if you're in gaming, the tribal casino expansion across the Southwest isn't slowing down. Your three-mile radius is shifting, and the properties that survive are the ones whose operators saw it coming and repositioned before the traffic counts forced their hand.

Read full analysis → ← Show less
Source: Google News: Casino Resorts
Airbnb Is Recruiting Creators to Sell Experiences. Your Local Demand Just Got a New Competitor.

Airbnb Is Recruiting Creators to Sell Experiences. Your Local Demand Just Got a New Competitor.

Brian Chesky says creators need Airbnb because their YouTube and TikTok income is drying up. The part he's not saying out loud is that 40% of experience bookings in Paris are already coming from locals, not travelers... and that changes what "competition" means for every hotel F&B outlet and programming budget in a tourist market.

Available Analysis

So here's what's actually happening. Airbnb is recruiting hundreds of social media creators to host paid experiences on its platform, and the pitch to those creators is basically: "Your ad revenue is shrinking, come monetize your audience through us instead." That's the headline. The part that should matter to hotel operators is buried three layers deep... this isn't about tourists anymore. In Paris, 40% of bookings for Airbnb's premium experiences are from locals. Not travelers looking for something to do between museum visits. Locals. People who live there. People who could be eating at your restaurant, attending your rooftop event, booking your spa package. Airbnb just found a way to use influencer marketing without paying for influencer marketing, because the creators ARE the product and they're bringing their own audience.

Look, I've been watching Airbnb's "Experiences" play since they launched it in 2016 and honestly... it was never the thing that kept me up at night. The execution was inconsistent, the supply was weird (how many "authentic pasta-making" classes does Florence need?), and most bookings came from travelers who were already on the platform shopping for a place to stay. It was a bolt-on. But this creator move changes the math in a way that matters. Creators don't just bring content. They bring distribution. A creator with 500,000 followers on TikTok hosting a "secret food tour" in your market isn't competing with your concierge recommendations. They're competing with your entire local programming strategy, and they're doing it with a marketing engine you can't match at property level. Airbnb charges these hosts a 20% commission. That's it. No build-out costs, no staffing headaches, no liquor license. The creator shows up, does their thing, Airbnb handles the transaction, and your potential F&B or experience revenue just walked out the door.

The timing is deliberate too. Chesky explicitly mentioned a "12-month window" to establish these vertical commerce categories before AI tools from the big tech companies start eating into consumer discovery. Translation: Airbnb is moving fast because they think the window to own experiential local commerce is closing. They're not wrong. And their Q1 numbers give them the runway to do it... $2.7 billion in revenue, $519 million in adjusted EBITDA, $1.7 billion in free cash flow. This isn't a cash-strapped company throwing things at the wall. This is a company with a 36% free cash flow margin making a calculated bet that the next growth vector isn't more nights booked... it's more spend captured per trip, plus an entirely new local demand channel that doesn't require anyone to sleep somewhere other than their own home.

Here's what I think most operators are going to miss. The instinct is to say "Experiences aren't my problem, I sell rooms." But Airbnb has been methodically adding services... grocery delivery via Instacart, airport pickups, luggage storage, car rentals... and now creator-led local experiences. They're building what tech people call a super app (I hate that term but it's accurate here). Every service they add is another reason for a traveler to stay inside Airbnb's ecosystem instead of discovering your property's offerings organically. And now they're adding a reason for LOCALS to use the platform who were never going to book a room in the first place. That's net new demand Airbnb is capturing that hotels never had a shot at... unless you were already programming events, experiences, and F&B that pulled from your local community. If you were, you just got a competitor with better distribution. If you weren't, you just lost a revenue stream you didn't know you were leaving on the table.

I talked to a hotel group last year that was trying to launch a "local experiences" program at three of their urban properties... curated neighborhood tours, chef's table dinners, that kind of thing. They spent six months building it out. Hired a coordinator. Built a landing page. Got maybe 30 bookings in the first quarter. You know what a creator with a local following could have done with that same concept and a single Instagram story? That's the asymmetry hotels are up against now. It's not about whether your experience is better (it probably is). It's about whether anyone knows it exists. Creators solve the discovery problem. Airbnb just made them the distribution channel AND the product simultaneously. That's actually clever. Annoyingly clever.

Operator's Take

If you're a GM at a full-service or lifestyle property in a top-25 market, this is your signal to audit your experiential programming... not next quarter, this month. Map every revenue-generating experience or event you offer to locals and ask yourself: could a creator on Airbnb replicate this without my building, my staff, or my overhead? If the answer is yes, you need to either differentiate hard or partner with local creators yourself before Airbnb signs them. For independent and boutique operators who've been building local community connections... your rooftop series, your chef collaborations, your neighborhood partnerships... that's your moat. Protect it. Double down on it. Make sure your direct booking channels surface those experiences as prominently as your room rates. And for anyone running F&B that's been coasting on hotel guest captive demand... the locals Airbnb is about to activate were never walking into your lobby anyway, but they represent the incremental revenue you should have been chasing. This is what I call the Three-Mile Radius. Your revenue ceiling isn't set by your room count... it's set by how much of the economic activity within three miles of your property you're capturing. Airbnb just started competing for that same three miles. Act accordingly.

— Mike Storm, Founder & Editor
Read full analysis → ← Show less
Source: Google News: Airbnb
Airbnb's CEO Sold $8.4M in Stock. Your OTA Problem Didn't Get Any Smaller.

Airbnb's CEO Sold $8.4M in Stock. Your OTA Problem Didn't Get Any Smaller.

Airbnb insiders unloaded over $45M in shares across three days while the company missed earnings estimates and launched new host protections. If you're an independent operator watching Airbnb expand its moat, the insider selling isn't the story... what they're building with the other hand is.

So here's something interesting. Between June 1 and June 2, Airbnb's CEO, CFO, and co-founder collectively sold roughly $45 million in company stock. Brian Chesky moved 62,764 shares for $8.4M. Joseph Gebbia's trust dumped 265,000 shares. The CFO sold another 7,400 shares on top of two previous sales in April and May. All pre-planned under 10b5-1 trading plans. All perfectly legal. All perfectly routine.

And I don't care about any of it.

Look, I get why insider selling makes headlines. It sounds dramatic. "CEO dumps millions in stock!" But 10b5-1 plans are literally designed to be boring... you set them up months in advance so you can sell without anyone accusing you of trading on inside information. Chesky still holds over 10.8 million shares. Gebbia's trust holds 3.4 million. These aren't people heading for the exits. They're diversifying, paying taxes, buying houses, whatever rich people do. The stock is trading around $133-136, analysts have price targets in the $162-168 range, and everyone with a Bloomberg terminal has already moved on.

What actually matters is what Airbnb is doing with its operational energy right now. They just launched earnings protection insurance for U.S. hosts. Think about that for a second. They're essentially telling potential hosts: "List your property, and if something goes wrong with your income, we've got a safety net." That's not a feature. That's a supply acquisition tool. Every new host listing that comes online because of that program is another unit competing with your hotel room on the same OTA search page. They're also building an AI lab, partnering with NASCAR venues, and cracking down on fake listings to improve platform trust. They missed their Q1 EPS estimate ($0.26 actual vs. $0.31 expected) but beat revenue by $60 million at $2.68 billion. That's a company investing in growth at the expense of short-term profit... which is exactly what should keep hotel operators up at night.

I talked to an independent owner a few weeks ago who told me he stopped tracking Airbnb supply in his market because "there's nothing I can do about it anyway." That's the most dangerous sentence in hospitality. There's always something you can do. But you have to actually understand what you're competing against. Airbnb isn't a startup anymore. It's a $85 billion distribution platform that's actively reducing friction for new supply to enter your market. The insider selling is noise. The host insurance product, the AI investment, the trust-building through listing verification... that's signal. And the signal says they're not slowing down.

The question nobody in our industry is asking loudly enough: what does your property offer that a well-reviewed Airbnb three blocks away doesn't? If your answer takes more than ten seconds, your guest already booked the Airbnb. That's not a technology problem. That's a value proposition problem. And no PMS upgrade or revenue management system is going to solve it for you.

Operator's Take

Here's what I want you to do this week if you're running an independent or a select-service in a leisure market. Go to Airbnb and search your zip code for your most popular weekend. Count the listings. Then count how many are new in the last 90 days. That number is your real comp set growth... not the new Hampton Inn down the road, but the 47 apartments and houses that just showed up on a platform with 2.68 billion dollars in quarterly revenue behind it. Now look at your own direct booking experience. Is it faster, easier, and more trustworthy than Airbnb's checkout flow? If it's not, that's your Monday morning project. You can't control their supply. You can control how hard you make guests work to book with you instead.

— Mike Storm, Founder & Editor
Read full analysis → ← Show less
Source: Google News: Airbnb
Your Revenue Manager Isn't Being Replaced by AI. They're Being Exposed by It.

Your Revenue Manager Isn't Being Replaced by AI. They're Being Exposed by It.

The hotel industry is celebrating AI-powered revenue forecasting as a "major upgrade." But the real upgrade isn't the technology... it's finding out which revenue managers were actually managing and which ones were just pulling yesterday's report and adding 3%.

Available Analysis

I worked with a revenue manager once... sharp woman, maybe ten years in the business... who kept a spiral notebook next to her keyboard. Every morning before she touched the RMS, she'd write down her rate recommendation for the day based on what she knew. Pickup pace, local events, weather, what the comp set was doing. Then she'd run the system and compare. Most days they matched within a few dollars. Some days they didn't, and those were the days she learned something. Either the system saw a pattern she missed, or she knew something the system couldn't possibly know (like the fact that a water main broke on the highway and half her expected arrivals weren't coming).

That notebook was her calibration tool. She was using the technology to sharpen her instincts, and her instincts to sharpen the technology.

Now I'm reading about the latest wave of AI-powered revenue management tools and the breathless coverage they're getting. McKinsey says hotels using AI see 17% revenue lifts and 10% occupancy gains. Vendors are claiming 35% RevPAR improvement and 40% ADR increases. The global hospitality tech market is supposedly hitting $30 billion by 2026 with a 25% growth rate. Those are big numbers. Some of them might even be true for specific properties in specific situations. But here's what nobody's telling you... the technology isn't the variable. The person sitting in front of it is.

I've seen this exact movie play out with every generation of revenue management technology for 25 years. First it was yield management systems in the late '90s. Then sophisticated RMS platforms in the 2000s. Then "big data" integration in the 2010s. Now it's AI. Every single time, the properties that got the most out of the new tools were the ones that already had disciplined revenue cultures. The properties that struggled kept struggling, just with more expensive software. A $2,000-a-month AI platform in the hands of a revenue manager who doesn't understand displacement analysis is a $2,000-a-month cost increase. Period.

The real story here isn't that the forecasts got better. It's that AI is about to make it painfully obvious who on your team actually understands revenue strategy versus who's been hiding behind "the system recommended it." When the system was a black box that spit out a number, a mediocre revenue manager could coast. When the system is showing you demand curves by micro-segment, competitive rate intelligence in real time, and channel-specific profitability... and you still can't explain why you're pricing $12 below the comp set on a compression night... that gap becomes visible to everyone. Including your owner.

The vendors aren't wrong that AI can improve forecasting accuracy. Of course it can. Processing speed data from dozens of sources, identifying patterns across thousands of booking windows, adjusting in real time for cancellations and pickup pace... machines are better at that than humans. They always will be. But forecasting is maybe 40% of revenue management. The other 60% is judgment, strategy, competitive positioning, understanding your specific market, knowing when to hold rate even when the algorithm says drop, and knowing when to drop even when your ego says hold. That 60% is human work. It's always been human work. And the hotels that treat AI as a replacement for that work instead of an amplifier of it are going to spend a lot of money to get mediocre results and wonder why the technology "doesn't work."

Operator's Take

If you're a GM at a select-service or full-service property, this is your opportunity to pressure-test your revenue function before the technology does it for you. Sit your revenue manager down this week and ask one question: "Walk me through how you'd price next Tuesday without the system." If they can't articulate a strategy based on market knowledge, pickup trends, and competitive intelligence... independent of whatever software you're running... you don't have a revenue manager. You have a button-pusher. And AI is about to make button-pushers obsolete. This is what I call the Vendor ROI Sentence... if your RMS vendor can't tie value to your P&L in one sentence, it's a story, not a solution. Before you sign for the next platform upgrade, make sure you've invested in the person who's going to use it. The best $3,000 you'll spend this year might not be on software. It might be on sending your revenue manager to an HSMAI workshop where they actually learn the discipline behind the dashboard.

Read full analysis → ← Show less
Source: Google News: CoStar Hotels
RevPAR Forecast Just Jumped From 0.6% to 2.8%. Don't Spend It Yet.

RevPAR Forecast Just Jumped From 0.6% to 2.8%. Don't Spend It Yet.

CoStar and Tourism Economics nearly quintupled their 2026 RevPAR growth projection on the back of a record Q1 and 8 million new room nights. The upgrade sounds like a victory lap... until you remember that expense growth is still outpacing revenue gains and the national number has never paid anyone's mortgage.

Available Analysis

I sat through an owner's budget meeting once where the asset manager projected 3% RevPAR growth for the coming year and the GM asked, "Does that come with 3% more housekeepers?" Nobody laughed. Because it wasn't a joke.

That's what I thought about when I saw CoStar and Tourism Economics revise their 2026 full-year RevPAR forecast from 0.6% to 2.8%. They announced it at the NYU hospitality conference on Monday, and on paper it looks like the industry just got a massive upgrade. Occupancy expectations moved from a projected decline to 62.8% (up from 62.3% in 2025). ADR growth went from about 1% to 2%. Year-to-date RevPAR through April came in at 4.0%, with Q1 posting the highest RevPAR on record. Room demand is up over 8 million room nights compared to the same period last year. HVS independently bumped their own forecast from 2.2% to 3.0%. Two different firms, same direction. That's not noise... that's signal.

But here's what you need to hear before you go celebrating. ADR growth of 2% is still running below inflation. Which means in real terms, your rate is flat or declining. You're selling more rooms (good), you're getting slightly more per room (less good), and your costs to service those rooms... labor, supplies, insurance, utilities... are climbing faster than the revenue they generate. The forecast itself acknowledges that expense growth is expected to outpace top-line gains and squeeze margins even as gross operating profit rises. So your hotel is busier. Congratulations. Are you more profitable? That's the question this headline doesn't answer, and it's the only question your lender cares about.

The luxury segment is projected to lead at 5.3% RevPAR growth, with broad demand gains across upscale, upper midscale, and midscale. That spread matters. For the last couple of years, luxury was eating everyone else's lunch while economy and midscale properties fought over scraps. If the demand growth is genuinely spreading downmarket, that's a structural improvement worth watching. But the national number is a blended average of 55,000+ hotels. Your property either outperformed it or it didn't, and the reasons have everything to do with your comp set, your market, and your team... and almost nothing to do with what got presented at a podium in Manhattan. This is what I call the National Number Trap. It's a weather report for an entire continent. You don't run your hotel based on whether it rained somewhere in Nebraska. You run it based on the three-mile radius around your front door.

Two things I'd pay attention to before you move on. Supply growth expectations got pulled back from 0.7% to 0.4%... which means fewer new hotels are opening than expected. That's demand-side tailwind for existing properties, especially in markets where pipeline delays have been chronic. And international inbound travel is now projected at 3.4% growth (a slight downgrade), while outbound travel from the U.S. was cut from 4.6% to 3.8%. More Americans staying home is good for domestic hotels. But don't confuse a forecast upgrade with a green light to get loose on spending. The macro environment is still uncertain. Consumer sentiment is soft. Gas prices are elevated. And we're one bad employment report away from a very different conversation. The Q1 record is real. The demand is real. The question is whether it holds through Q3 and Q4 or whether we're front-loading a year that softens in the back half. I've seen this movie before. Strong first half. Conference presentations full of optimism. Then September arrives and the phone calls change tone.

Operator's Take

If you're a GM or director of revenue at a branded property, here's what to do this week: pull your flow-through from Q1 and run your actual GOP margin against this RevPAR growth. If your top line grew 3-4% and your GOP grew less than 2%, you're on a treadmill. Take that number to your ownership meeting before someone else takes the headline number and assumes you're printing money. For revenue managers in upper midscale and midscale properties, the demand broadening is your window to push rate... carefully. Don't discount to fill. The occupancy forecast already moved in your favor. Hold your rate integrity and let demand come to you. And for everyone watching supply in your market, go check your pipeline reports. If construction delays pushed a competitor's opening past 2026, that's found time. Use it to capture share, not to relax.

Read full analysis → ← Show less
Source: Google News: CoStar Hotels
Monarch's CEO Sold $604K in Stock the Day After Hitting an All-Time High. The Timing Is Interesting.

Monarch's CEO Sold $604K in Stock the Day After Hitting an All-Time High. The Timing Is Interesting.

Monarch Casino & Resort just posted record Q1 numbers and its stock touched $121.87. Then the CEO sold 5,000 shares the next day. The 8-K filing is routine, but what's underneath it tells you something about how family-controlled casino operators think about capital... and what tech-forward operators should be watching.

So here's a filing that most people will scroll past. Monarch Casino & Resort dropped an 8-K on May 27 covering its annual stockholder meeting... director elections, advisory vote on executive comp, the usual SEC compliance stuff. Standard. Boring. Except buried in the context around this filing is a data point that caught my attention: CEO John Farahi sold 5,000 shares the day after MCRI hit an all-time high of $121.87, pocketing $604,200. That's 0.8% of his holdings. Not a fire sale. Not a panic move. But when a CEO of a family-controlled operation takes chips off the table at the peak, it's worth asking what he sees that the "strong buy" analysts don't.

Look, I'm not a stock analyst (that's Jordan's lane). What I am is someone who pays attention to how casino resort operators deploy technology and capital, and Monarch's playbook is genuinely interesting here. They reported Q1 revenue of $136.6 million, up 8.9% year-over-year, with adjusted EBITDA growth of 19%. Those are strong numbers for a two-property operator running a casino resort in Reno and another in Black Hawk, Colorado. But what actually caught my engineering brain is the company's stated strategy around technology... they're explicitly talking about deploying tech to reduce operating costs and improve efficiency across both properties. That's not a marketing line from a vendor pitch deck. That's an operator saying "we're going to use systems to protect our margins." The question, as always, is what that actually means at property level.

Here's where I get interested and skeptical in equal measure. Monarch is running significant hotel room renovations at their Reno property while simultaneously pushing technology adoption. I've seen this movie before... a property group tries to upgrade physical product AND modernize systems at the same time, and the staff on the floor ends up juggling new room configurations, new tech workflows, and guest expectations that shift mid-renovation. I consulted with a casino hotel group last year that tried exactly this. New PMS rollout during a tower renovation. The front desk team was learning a new system while explaining to guests why their "premium room" was next to an active construction zone. Complaints went up 40% in the first quarter. Not because the tech was bad or the renovation was bad... because nobody planned for both hitting the same team at the same time.

The other thing worth noting for operators watching Monarch's approach: this is a company that returned $17.6 million to stockholders through share repurchases in Q1 alone, on top of a $0.30 per share dividend. When a two-property operator is buying back that much stock while renovating and investing in technology, the capital allocation math gets tight. Every dollar going to buybacks is a dollar not going to infrastructure... and I mean actual infrastructure, not just room finishes. I'm talking about the network backbone, the property management integrations, the stuff behind the walls that determines whether your "technology-driven efficiency" strategy actually works or just looks good in the earnings call script. The question I'd be asking if I were evaluating their tech stack is simple: what's the actual IT capital budget relative to the renovation spend? Because in my experience, when the visible renovation gets 90% of the capital and the invisible infrastructure gets 10%, you end up with beautiful rooms running on systems that crash at 2 AM.

Monarch's results are genuinely strong... 38.9% net income growth is not nothing. But for operators watching a family-controlled casino company navigate technology adoption, renovation, and capital return simultaneously, the lesson isn't "do what Monarch does." The lesson is that even the best-performing operators face a sequencing problem. You can do all three. You probably can't do all three well at the same time without something getting shortchanged. And the thing that gets shortchanged is almost always the technology infrastructure, because it's the one thing guests don't see and boards don't ask about... until it breaks.

Operator's Take

If you're running a casino resort property or any full-service hotel that's trying to renovate and upgrade technology simultaneously... stop and sequence it. I've seen this go wrong enough times to know: your team cannot absorb a new PMS, a new workflow, AND a construction disruption in the same quarter without service degradation. Map out which floors or wings are under renovation and stagger your tech rollout to the unaffected areas first. Get your staff trained and comfortable on the new systems before you add renovation chaos to their plate. And if your ownership group is pushing both timelines to overlap because "we want it done by Q4"... bring them the data on what simultaneous rollouts cost in guest satisfaction scores. That's a conversation worth having before it becomes a problem worth fixing.

— Mike Storm, Founder & Editor
Read full analysis → ← Show less
Source: Google News: Casino Resorts
Primm Valley Paid the Price for Standing Still Between Two Markets That Moved

Primm Valley Paid the Price for Standing Still Between Two Markets That Moved

Three casino resorts that once pulled 2,600 rooms of California traffic off I-15 are going dark by July 4th. The closure is a textbook case of what happens when your competitive moat evaporates and nobody builds a new one.

Available Analysis

I worked with a guy years ago who managed a property right off a major interstate exit. Location was everything. Travelers had to stop... there was literally nowhere else to go for 40 miles in either direction. He used to say "we don't need to be great, we just need to be here." And for a long time, that was true. Then a competitor opened 20 miles south. Then another one 15 miles north. Within three years his occupancy dropped 30 points and his ADR followed it down. He kept saying "but we're the original." Nobody cared. The travelers had options now, and his "we just need to be here" strategy turned out to be no strategy at all.

That's Primm. For decades, those three properties... 2,642 rooms, 137,000 square feet of casino floor, nearly 3,000 slot machines... existed because geography gave them a monopoly. You're driving from LA to Vegas, you need gas, you want to pull a slot handle, maybe stay overnight. Primm was the only game on that stretch of I-15. Then California's tribal casinos started expanding (Proposition 1A in 2000 gave them slot machines, and the build-out has been relentless ever since). Why drive to the Nevada border when you can gamble 45 minutes from home? The customer base didn't shrink gradually. It evaporated. And now the last property standing, Primm Valley Resort, closes July 4th. Three hundred and forty-four people lose their jobs. The ones living in company housing have two days after closing to be out.

Here's the part that should sting for anyone in operations. Affinity Gaming didn't ignore the problem. They tried to right-size. Closed Whiskey Pete's in December 2024. Moved Buffalo Bill's to events-only in mid-2025. Renovated. Adjusted. The CEO told the Nevada Gaming Control Board the property has been losing money for years despite investment. They did everything the playbook says to do... except the one thing that might have mattered, which is fundamentally reimagining what Primm was FOR. You can't right-size your way out of an existential problem. Trimming a business model that no longer works just means you're losing money more slowly.

Think about the timeline here. Herbst Gaming bought these three properties from MGM Mirage in 2007 for $400 million. That's roughly $151,000 per key across the portfolio. Today, nobody's buying at any price. There's a potential buyer sniffing around (a travel center operator interested in maybe reopening Whiskey Pete's), but the Primm family who owns the land says no deal is close. The distance between $400 million and "maybe someone will take one of these off our hands" is the entire story of what happens when your competitive advantage was never really yours... it was just geography, and geography stopped being enough.

This isn't just a casino story. Every hotel operator sitting on a location-dependent asset should be paying attention. If the only answer to "why do guests choose us?" is "because we're here," you're one competitor, one bypass road, one shift in travel patterns away from being Primm. The properties that survive market shifts are the ones that give people a reason to come, not just a reason to stop. That old night auditor's notebook, the $40K guest satisfaction platform, the revenue management system... none of it matters if the fundamental question of why you exist doesn't have an answer anymore.

Operator's Take

If you're running a property where location is your primary demand generator... an interstate exit, a remote stretch of highway, the only game near an airport or military base... take an honest hour this week and write down every competitive threat that could change that equation in the next five years. New supply. A road project that reroutes traffic. A tribal gaming expansion. A competitor's renovation that makes your product look tired. Then ask yourself: if that demand generator disappears, what's your second reason to exist? If you don't have one, start building it now. Primm had 25 years of warning that the California tribal casinos were coming for their customer base. Twenty-five years. And the answer was still "we're the stop on I-15." Don't be the operator who learns this lesson from someone else's closure when you could be learning it from your own honest assessment today.

Read full analysis → ← Show less
Source: Google News: Casino Resorts
Three Hotel Chains Just Walked Away from Cuba. The June 5 Deadline Explains Everything.

Three Hotel Chains Just Walked Away from Cuba. The June 5 Deadline Explains Everything.

Iberostar, Blue Diamond, and Meliá are pulling out of Cuba under crushing U.S. sanctions pressure, but the real lesson isn't about geopolitics. It's about what happens when infrastructure collapse meets brand standards and the operator has to choose between the flag and the building.

Available Analysis

I worked with a GM once who was running a resort in a market where the power went out every other day. Not brownouts. Full blackouts. Generators kicking on, guests standing in dark hallways, kitchen shutting down mid-service. He told me something I never forgot: "You can manage through a bad week. You can manage through a bad month. But when the infrastructure itself is broken... when the water pressure, the electricity, the supply chain are all failing at the same time... you're not managing a hotel anymore. You're managing a disaster with a reservation system."

That's Cuba right now. And three major hotel companies just made the same calculation within days of each other.

Iberostar is walking away from 12 properties effective tomorrow, June 1. Blue Diamond pulled its brands (Royalton, Memories, Starfish, and others) immediately. Meliá, which still has roughly 34 hotels and 5,000-plus rooms on the island, closed half its capacity in Q1 and posted a 68% drop in net profit with occupancy running at 34.1%. Let me say that number again. 34.1% occupancy. At a resort destination. In the Caribbean. That's not a soft patch. That's a market that has stopped functioning.

The stated reasons are a cocktail of severe blackouts, food shortages, supply chain collapse, and "operational limitations"... which is corporate-speak for "we literally cannot deliver the product our brand promises." But let's be honest about the accelerant here. On May 7, the U.S. designated GAESA (Cuba's military-run business conglomerate that controls most of the hotel infrastructure through its subsidiary Gaviota) as a sanctioned entity. Foreign companies got until June 5 to cut ties or face secondary sanctions. That's not a negotiation. That's an ultimatum. And layered on top of that, there are roughly 6,000 claims under the Helms-Burton Act valued at close to 8 billion euros targeting properties built on expropriated land. Iberostar and Meliá are both exposed. So the question stopped being "can we make this work?" and became "how fast can we get out before this gets worse?"

Here's what I keep coming back to, though. The sanctions are the trigger, but the infrastructure collapse was the underlying condition. These companies were already bleeding. Meliá didn't lose 68% of its net profit because of a May 7 executive order. That happened because the island's electrical grid, water systems, and food supply have been deteriorating for years. The sanctions just made it impossible to pretend the situation was temporary. I've seen this pattern before in different contexts... operators hanging on in a deteriorating market because they've got sunk cost, because they've got relationships, because they keep telling themselves "next season will be better." And then something external forces the decision they should have made 18 months ago. The exit isn't the failure. The failure was staying too long. And look... I'm not second-guessing the people who made these decisions. Running hotels in markets with collapsing infrastructure is a special kind of hell. You're asking your team to deliver a guest experience with unreliable power, inconsistent food supply, and a political environment that changes by the week. At some point, the brand promise and the operational reality diverge so far that keeping your flag on the building does more damage to the brand than pulling it. This is what I call the Brand Reality Gap. The brand sells a promise... in this case, a Caribbean resort experience with everything that implies. The property delivers that promise shift by shift, room by room. When the gap between promise and delivery becomes unbridgeable (and 34% occupancy tells you guests have already figured it out), the flag comes down. Not because anyone wants it to. Because the math and the guest experience both demand it.

The question nobody's asking yet: what happens to the 5,000-plus Meliá rooms still on the island? To the staff at those 12 Iberostar properties? To the Canadian tour operators who were still selling Cuba packages? Air Canada, WestJet, and Transat have already been pulling back for months. The Canadian government has Cuba at "avoid non-essential travel." This isn't a temporary disruption. This is an entire destination falling off the map for international hotel brands. And for anyone watching from a different market with their own infrastructure headaches... pay attention. The distance between "manageable challenges" and "we're pulling our flag" is shorter than you think.

Operator's Take

This one's not about your property. But it IS about your playbook. If you're operating in any market where infrastructure is fragile (aging electrical, water system issues, unreliable municipal services), build your contingency plan now, not when the crisis hits. Know exactly how many consecutive days you can operate on generator power. Know your food and supply alternatives if your primary vendors go dark. And if you're a management company operating internationally under a U.S.-connected brand, get with your legal team this week and map every property against current and potential sanctions exposure. The June 5 GAESA deadline caught some operators with barely 30 days to unwind entire portfolios. That's not enough time. The operators who survive geopolitical risk are the ones who've already gamed out the exit before they need it.

Read full analysis → ← Show less
Source: Google News: Resort Hotels
Las Vegas Gaming Revenue Is 24% of Total Resort Revenue. The Pool Party Is the Business Now.

Las Vegas Gaming Revenue Is 24% of Total Resort Revenue. The Pool Party Is the Business Now.

Las Vegas's largest resort operators now generate roughly three-quarters of their revenue from non-gaming sources, with individual dayclubs pulling over $1 million on a single Saturday. The question for hotel investors isn't whether this model works in Vegas... it's what happens when the visitor count drops 7.5% while you're charging premium prices.

Gaming revenue on the Las Vegas Strip hit a record $8.82 billion in 2025. MGM Resorts derived 23.4% of total revenue from gaming operations. Caesars: 27.6%. Wynn: 24.1%. The rest (rooms, F&B, entertainment, retail, and yes, dayclubs) now accounts for roughly 75 cents of every dollar these companies collect.

That inversion has been building for 25 years. Non-gaming revenue surpassed gaming on the Strip in 1999. By 2015, it was 65.3% of total revenue. The trajectory hasn't reversed. What's changed is the composition of that non-gaming bucket. Encore Beach Club reportedly generates over $1 million in revenue on Saturdays. A single dayclub. One day of the week. Nevada collected $1.22 billion in combined gaming and live entertainment taxes in 2025, with the Live Entertainment Tax running 10% on admission, food, and merchandise at venues under 7,500 capacity. The state itself has restructured its fiscal apparatus around the entertainment economy.

Here's the number that should concern anyone underwriting a Las Vegas asset right now: overall tourism declined 7.5% in 2025 versus 2024. Hotel occupancy, ADR, and RevPAR all decreased. The lowest annual visitor total since 2021. Strip premium pricing is cited as a primary factor. Off-Strip casinos offering value-oriented experiences are growing. So you have a market that broke records on gaming revenue and simultaneously lost visitors. That's a concentration risk. The high-value customer is spending more. The volume customer is leaving. I've analyzed portfolios where this exact pattern preceded a sharp correction... not because the top line collapsed, but because the customer base narrowed until one macro shock exposed the fragility.

The "dayclub economy" framing is catchy, but decompose it. A dayclub generating $11 million annually at a resort collecting billions is a rounding error on the P&L. It's a high-margin rounding error (F&B margins on bottle service are extraordinary), but the strategic significance is in what it signals about customer acquisition, not what it contributes to NOI. The dayclub is the funnel. The room night at $500+ ADR is the revenue. The $400 dinner reservation is the revenue. The show ticket is the revenue. When you're modeling a Vegas asset, the dayclub isn't a line item. It's a marketing expense that happens to generate income.

The risk I'd flag for anyone holding or acquiring Strip-exposed assets: this model requires a specific consumer. Young, high-disposable-income, experience-motivated, price-insensitive. That consumer showed up in 2023 and 2024. In 2025, with visitor volume down 7.5% and the Culinary Union publicly attributing the decline to rising prices, the question is whether the pricing elasticity has been tested to its limit. Record gaming revenue masking a tourism decline is not a sign of strength. It's a warning that the base is narrowing. And narrow bases break.

Operator's Take

Look... if you're an owner or asset manager with Strip-adjacent or Las Vegas exposure, the record gaming revenue headline is not your friend. Pull your trailing 12-month visitor mix data. What percentage of your occupied rooms are tied to the high-spend entertainment customer versus the traditional leisure tourist? If that ratio has shifted more than 10 points in two years, you're concentrating risk whether you realize it or not. Run a stress test at 15% visitor decline with current ADR. If your debt service coverage breaks below 1.25x in that scenario, you need to have a conversation with your lender before your lender has a conversation with you. The pool party economy works until it doesn't, and a 7.5% visitor drop in a record revenue year is the canary.

— Mike Storm, Founder & Editor
Read full analysis → ← Show less
Source: Google News: Casino Resorts
Disney Just Opened Its Booking Engine to a Hyatt. Every Off-Site Hotel in Orlando Should Be Paying Attention.

Disney Just Opened Its Booking Engine to a Hyatt. Every Off-Site Hotel in Orlando Should Be Paying Attention.

The Hyatt Regency Grand Cypress can now be booked as part of a Walt Disney World vacation package directly through Disney's website. That sounds like a nice press release... until you think about what it means for the 400-plus other hotels within shuttle distance of the Magic Kingdom that just lost a competitive edge they didn't know they had.

Available Analysis

I've seen this movie before. Not with Disney specifically, but with the pattern underneath it. A dominant demand generator in a market... a convention center, a casino, a theme park... decides to extend its booking ecosystem to include a select few third-party properties. And everyone focuses on the property that got picked. The real story is what happens to the properties that didn't.

Xenia Hotels & Resorts owns the Hyatt Regency Grand Cypress. They paid $205.5 million for it back in 2017. That's roughly $252K per key for an 815-room resort sitting on 1,500 acres with a Jack Nicklaus golf course and a Michelin-recommended restaurant. It was already one of the strongest off-site plays in the Orlando market. Now Disney is letting guests book it directly through disneyworld.com as part of a bundled vacation package... theme park tickets, hotel, shuttle transportation, one checkout. That's not a marketing partnership. That's distribution infrastructure. Disney just handed this property a booking channel that reaches tens of millions of vacation planners who never leave the Disney ecosystem to shop. Think about that. A family planning a Disney trip goes to Disney's website, and instead of only seeing Disney-owned resorts at $400-600 a night, they now see a Hyatt option that probably comes in lower with arguably better amenities. Complimentary shuttles to the Transportation and Ticket Center, EPCOT, and Disney Springs included.

Here's what nobody in the press releases is talking about. Disney doesn't do this out of generosity. They do this because their own resort inventory has constraints... pricing, availability, capacity during peak periods... and every family that gets sticker shock and books off-site entirely is a family that might not buy the ticket bundle, might not book through Disney's channel, might not spend as much in-park. By pulling a high-quality off-site property INTO the Disney booking funnel, they keep the guest inside their commercial ecosystem even when the guest sleeps somewhere else. That's brilliant, frankly. And it should terrify every other off-site hotel operator in the Orlando market who's been competing on proximity and shuttle service as their differentiator. Because proximity and shuttle service just became table stakes for the property Disney chose... and irrelevant advantages for the ones they didn't.

I worked in a market once where the convention center started a "preferred hotel" program. Five properties got listed on the convention center's website with direct booking links. Those five saw a measurable lift in group business within 90 days. The other 30 hotels in the comp set? Their sales teams suddenly had to work twice as hard to get the same leads they used to get organically. Nobody's hotel got worse. The distribution landscape just shifted underneath them overnight. That's what's happening in Orlando right now, except the demand generator isn't a convention center with 200,000 attendees a year. It's Walt Disney World with 58 million.

The financial terms between Disney and Hyatt/Xenia haven't been disclosed, and they won't be. But make no mistake... there's a cost baked in somewhere. Commission structure, rate parity requirements, brand standards for the shuttle experience, something. Disney doesn't give away shelf space on their booking platform for free. The question for Xenia's asset management team is whether the incremental demand justifies whatever that cost turns out to be. For an 815-key resort property, even a 3-4 point occupancy lift from Disney channel bookings could move the NOI needle significantly. And for every other off-site hotel operator in Orlando who just watched a competitor get handed the most powerful leisure booking channel in the country... the question is what you're going to do about it before your next budget cycle.

Operator's Take

If you're running an off-site hotel in the Orlando market, this changes your competitive position whether you acknowledge it or not. The Hyatt Regency Grand Cypress just got access to a demand channel you can't buy your way into. Your move is to audit your own value proposition honestly this week. What are you offering Disney-bound guests that they can't get at the Grand Cypress with a Disney shuttle included? If the answer is "lower rate," that's a race to the bottom. If you have something real... location, a specific amenity, a family experience, a loyalty play... double down on it in your OTA descriptions, your Google profile, your direct booking messaging. And watch your comp set data like a hawk over the next two quarters. The shift won't show up in one month's STR report. It'll show up in your booking pace for Q4 and holiday season. See it coming before it arrives.

Read full analysis → ← Show less
Source: Google News: Hyatt
Caesars Is Done Buying Gamblers. Now They're Harvesting Them.

Caesars Is Done Buying Gamblers. Now They're Harvesting Them.

Caesars Digital just posted record Q1 revenue of $374 million while spending less to acquire customers, and their secret weapon is the same loyalty program that fills your hotel rooms. If you're running a Caesars-affiliated property, the sportsbook strategy is about to change what walks through your lobby door.

I worked with a casino resort GM once who kept two whiteboards in his office. One tracked gaming revenue. The other tracked what he called "the real number"... total property spend per guest, broken out by how they found the place. Loyalty program guests outspent walk-ins by 40% on rooms, F&B, and spa. Not because they were richer. Because the program had already trained them to spend. Every dollar Caesars puts into that rewards ecosystem comes back through your rate, your minibar, your steakhouse check. That GM understood something most hotel operators don't think about enough... the acquisition channel shapes the guest behavior long after check-in.

So here's what's happening at Caesars Digital, and why it matters even if you've never placed a bet in your life. Their sportsbook division just hit $374 million in first-quarter net revenue, up nearly 12% year over year. But here's the part that should get your attention... they did it while mobile betting volume actually dropped 3%. Revenue up, volume down. That means they're squeezing more out of every player. Average revenue per monthly unique player jumped 15% to $219. Hold percentage climbed to 8.3%, up from 5.4% a couple years ago. CEO Tom Reeg called it the "free cash flow harvesting stage." That's not a throwaway line. That's a strategic declaration. They're done spending wildly to acquire new bettors. They're monetizing the ones they already have. And they're doing it through the Caesars Rewards program... the same program that drives room nights, comps, and tier-based loyalty across the entire property portfolio.

This matters to hotel operators because the profile of the guest walking through your doors is shifting. Caesars isn't running $1,000 risk-free bet promotions anymore to lure in casual bettors who'll never come back. Their current offer... bet a dollar, get ten profit boosts capped at $25 each... is designed to keep existing users engaged, not to create new ones from scratch. That's a fundamentally different acquisition philosophy. It means the sportsbook is feeding the loyalty program more efficiently, which means the guests being driven to Caesars properties are increasingly repeat, higher-value, rewards-motivated travelers. If you're operating a Caesars-affiliated hotel, your comp mix is going to look different. More loyalty-driven bookings, fewer transient walk-ins chasing a Super Bowl promo they saw on Instagram.

There's another move here worth paying attention to. Caesars pulled credit card deposits from their sportsbook platform back in April, joining DraftKings, FanDuel, BetMGM, and bet365 in what's become an industry-wide shift. The responsible gambling angle is real and it matters. But from an operational perspective, it also means the sportsbook customer base is self-selecting for people with actual bankrolls, not people borrowing from Visa to chase a parlay. That's a healthier customer for your hotel too. Someone funding a sportsbook account with a debit card or bank transfer is more likely to be a planned-trip, budgeted guest than an impulse gambler on a credit card bender. The downstream effect on your property... fewer comps going to guests who were never going to spend beyond the freebie, more comps going to guests who are already in the spending mindset.

The bigger picture here is that Caesars is proving something the rest of the industry should study. They figured out that the most expensive thing in any customer relationship is the first transaction. Once you own that customer through a loyalty ecosystem that crosses digital betting, hotel stays, dining, and entertainment... you stop paying acquisition costs and start collecting margin. The sportsbook isn't a standalone business anymore. It's a funnel. And the hotel is where the funnel delivers its highest-margin output. If you're on the Caesars platform, understand that dynamic and lean into it. If you're not, understand that your competitors who ARE on it are getting guests pre-qualified by a digital engagement engine you don't have access to.

Operator's Take

If you're a GM at a Caesars-affiliated property, pull your loyalty contribution numbers for Q1 and compare them to the same period last year. I'd bet they're up, and if they are, that's not an accident... it's the direct result of this digital strategy shift. Build your forecasting around higher loyalty mix, not higher volume. That means your rate integrity on loyalty bookings matters more than ever because these guests are worth more over their lifetime. Talk to your revenue manager about protecting rate on rewards-driven segments instead of discounting to fill gaps. And if you're running F&B or entertainment, look at your Caesars Rewards redemption data... that's where the incremental spend lives now. The sportsbook is doing the prospecting for you. Your job is to convert the visit into a repeat stay.

Read full analysis → ← Show less
Source: Google News: Caesars Entertainment
Singapore Is Printing Money for Sands. Macao Is the $16 Billion Question.

Singapore Is Printing Money for Sands. Macao Is the $16 Billion Question.

Las Vegas Sands just posted $788 million in EBITDA from a single property in Singapore while Macao margins quietly shrank. The CEO says he wants higher margins in Macao, but the strategy he's deploying there is designed to do the opposite... at least for now.

Available Analysis

I worked with a GM once at a two-property operation... one hotel was a cash machine, the other was a project. Every Monday morning, the owner would look at the combined P&L and feel pretty good about life. And every Monday morning, that GM knew the truth: the strong property was masking the fact that the weaker one was slowly eating itself. The combined number was a lie they both agreed to believe.

That's what I see when I look at Las Vegas Sands right now. Marina Bay Sands in Singapore just threw off $788 million in adjusted property EBITDA in a single quarter. A 53% operating margin. From one building. That is a staggering number... roughly $8.6 million a day in EBITDA from one integrated resort. Meanwhile, the five Macao properties collectively generated $633 million in EBITDA, with margins that actually compressed year-over-year... 29.9% versus 31.3% a year ago. Five properties generating less EBITDA than one, with shrinking margins. And the CEO says the plan in Macao is to spend more aggressively on customer incentives to chase market share. That's not a margin improvement strategy. That's a volume play dressed up in margin language, and anyone who's ever run a hotel knows the difference.

Here's what's really happening. Macao's gross gaming revenue has plateaued around $28 billion annually. The junket business that used to drive premium play is essentially gone. Online gambling is siphoning off the casual customer. Visitor spending habits have fundamentally changed. So Sands is doing what operators always do when the market shifts... they're buying revenue with promotional spending. That can work. I've seen it work. But let's not pretend that "being more aggressive with customer incentives" is a path to higher percentage margins anytime soon. The CEO has essentially said as much publicly... the bet is that higher absolute EBITDA (more total dollars) justifies thinner percentage margins. That's a legitimate strategy. Just don't call it a margin improvement story when the margins are moving in the wrong direction.

The Singapore side is fascinating for a different reason. Sands is pouring $8 billion into expanding MBS... a fourth tower, 570 luxury suites, a 15,000-seat arena, more convention space. They took on a $9 billion loan to finance it. The property already runs at 94-99% occupancy with full exhibition halls, so the demand case is real. But here's the thing that should make every operator's antenna go up: when you take a property running at 53% margins and you add $8 billion in development cost, your breakeven math changes dramatically. The expanded MBS will need to generate substantially more revenue just to maintain its current return profile once that debt service kicks in. The current MBS is the single most profitable hotel-casino asset on the planet. The expanded MBS is an $8 billion bet that lightning strikes the same spot twice but bigger. History suggests that's harder than it sounds.

What I'm watching is the gap between the narrative and the numbers. The consolidated picture looks great... $3.59 billion in revenue, up 25%. The stock took an 8.6% hit after earnings anyway because Wall Street did what Wall Street does... it looked past the Singapore headline and found the Macao margin compression underneath. LVS repurchased $740 million of stock in the quarter while carrying $16 billion in weighted average debt. They're simultaneously expanding, buying back shares, paying dividends, and trying to fix a market (Macao) where the structural dynamics have fundamentally shifted. Something in that equation eventually has to give. The question is whether Singapore can keep throwing off enough cash to fund everything else. Right now, it can. The word "right now" is doing a lot of heavy lifting in that sentence.

Operator's Take

Look... this story is about a $58 billion gaming company, but the underlying dynamic is something every multi-property operator lives with. If you're running a portfolio where one asset is carrying the others, don't let the combined P&L lull you into complacency. This is what I call the Flow-Through Truth Test. Revenue growth at the Macao properties was 23.7% year-over-year, but EBITDA margins shrank. That means incremental revenue is costing more to generate than the existing base... the flow-through is deteriorating. If you're seeing that pattern at any of your properties (top line growing but GOP margin compressing), stop celebrating the revenue line and start interrogating where the money is going. Pull your promotional spend, your loyalty program costs, your OTA commissions as a percentage of revenue and trend them quarterly. If those lines are growing faster than revenue, you're on the same treadmill Sands is running in Macao. The difference is they have a Singapore printing press to fund it. You probably don't.

Read full analysis → ← Show less
Source: Google News: Las Vegas Sands
End of Stories